Advancing Financial Health and Resilience
Building financial resilience and well-being together
Why financial health and resilience matter for people, businesses, communities and future generations
Households, employees, SMEs and communities face profound uncertainty: affordability pressures, geopolitical uncertainty, extreme weather, technological disruption, financial stressors, shocks and planned and unplanned events. These pressures affect health, well-being, housing, employment, economic growth and community resilience.
Financial health and resilience can influence and shape people’s ability to manage their day-to-day financial obligations, live with dignity, cope with unexpected shocks, achieve their goals and feel secure and confident in their financial futures. Improved business financial health and resilience of MSMEs supports business continuity, protects livelihoods, enables investment, job creation and economic growth.
While organizations use slightly different definitions, our definitions of financial health, financial resilience, financial wellness and financial well-being set out in the Financial Well-Being Framework created in 2016 and published in 2017, are closely aligned with core G20 Policy Note on Financial Well-Being created with OECD; the Financial Well-Being Conceptual Model and Preliminary Analysis developed by Professor Kempson in 2017, followed by extensive financial well-being research and practice; and CFPB’s definition of financial well-being, scale and tool published in 2015[1].
As articulated by Fernando Restoy, Chair of the Financial Stability Institute at the Bank of International Settlements, in his speech ‘From the periphery to the core: financial health and central banks’ mandates’ published by BIS on October 14, 2026, financial instability can undermine household financial health through job and income losses, declining asset values and reduced access to credit. Monetary instability, particularly high inflation, can erode purchasing power, diminish the real value of savings and make it harder for households to manage their finances and plan. While household financial health supports financial stability, core to central banks’ mandate, spending, saving and managing debt, aggregated nationally, become relevant to monetary policy: a two-way relationship.
Understanding and measuring the financial health and resilience of households, SMEs and communities at the macro and micro levels enables earlier identification of emerging vulnerabilities and more targeted, evidence-based action. For central banks and financial authorities, this evidence can inform forward-looking monetary policy, financial regulation and supervision, supporting financial stability. For government policymakers, it can strengthen three interconnected policy areas: social policy, targeting support to reduce vulnerability and improve well-being; fiscal policy, directing taxation, public spending and transfers more effectively; and economic development policy, supporting MSMEs’ resilience, investment, productivity and job creation.
Measuring impact over time helps assess which policies and interventions improve outcomes, for whom and under what conditions, enabling more targeted strategies, effective allocation of resources, impact innovation and accountability.
Helping people and organizations build their financial health and resilience throughout their lives, while fostering their overall resilience, can create multiple and interconnected social, financial, economic and sustainable outcomes. Stronger resilience can support greater financial security and confidence, improved overall well-being, more sustainable businesses, stronger employment and more inclusive, resilient, thriving communities.
Improved financial health and resilience align closely with six key Sustainable Development Goals and the Purpose, Vision and Impact goals and priorities of our non-profit.
The evidence tells us that action is needed
Financial Resilience Institute’s research demonstrates the scale of financial vulnerability, and the opportunities for more effective, targeted action.
For example In February 2026, Canada’s Mean Household Financial Health Score was 53.34, with households just ‘Approaching Resilience’ nationally, but 74% of households having some level degree of financial vulnerability, and significantly increased financial vulnerability for many populations, including those facing systemic barriers.
Financial resilience mobility is also real. Our Institute’s longitudinal research and Financial Health and Resilience Index analytics and reports demonstrate that people can improve their financial resilience within months by saving more, planning ahead financially, adjusting financial and consumer behaviours and accessing relevant products, services, interventions and supports, helping them achieve life and financial goals.
People and businesses can also slip backwards. Households and populations facing systemic barriers and greater financial vulnerability may require ongoing, targeted social, financial or economic development support. With financial health and resilience being the inverse of financial vulnerability, measuring changes and intervention outcomes over time is essential.
Households financially affected by extreme weather events similarly have a Mean Financial Resilience Score of 49.3 as of February 2026, compared with 54.5 for those not affected. The financial vulnerability gap widened from 3.9 Index points in February 2024 to 5.2 points in February 2026.
Based on our Canadian SMEs 2026 Business Financial Health and Resilience Report, 73% of SMEs want to better understand and improve their business financial health and resilience, while 46% reported costs rising faster than revenues and 36% experienced high financial stress. 84% believe financial institutions could do more to support their business financial resilience as of December 2025.
By focusing on the financial health and resilience of households, MSMEs and communities, financial authorities, financial institutions, policymakers, employers and others can achieve multiple benefits. For financial authorities and central banks, measurement can complement traditional indicators, potentially revealing vulnerabilities before loan arrears and credit losses emerge. Financial institutions can identify risks earlier, encourage healthy financial behaviours and provide relevant products, services and advice, strengthening trust, relationships, business benefits and long-term sustainability. Policymakers can target resources more effectively, improving quality of life, well-being and economic participation. Employers can reduce financial stress and improve productivity, well-being, engagement and retention. For households themselves, improved financial health and resilience strengthen their capacity to plan, pursue opportunities and adapt to economic uncertainty, climate-related events and emerging challenges.
Financial inclusion does not automatically improve financial health. Digital innovation and AI present opportunities and risks, alongside fraud and scams. Measurement and evidence-based decision-making enable timely, targeted strategies, policies and interventions.
A financial system’s resilience depends partly on the people it serves. Advancing financial health and resilience contributes to global goals and a more sustainable world: building stronger communities, more resilient, inclusive economies and improved lives.
Financial Vulnerability as a Mainstream Issue
While our work is international, see this video on financial vulnerability as a mainstream issue in Canada, building on our Institute’s extensive reports published since 2017 and world-leading Financial Health and Resilience Index.
Behind these numbers are people, families and business owners managing today while building for the future, and clear opportunities for financial institutions, governments, employers, non-profits and other purpose-led organizations to help.
Check your free individual financial resilience score tool and access independent resources to help you move forward, with this being used by valued clients such as Co-operators for good.
Alternatively, access our Institute’s open-source Financial Well-Being Index Model and Toolkit linked to an overall personal well-being score for your organization or community, or learn more about the Business Financial Health and Resilience of SMEs in India, including Women-Led SMEs.
When individuals and businesses thrive, so do families, communities and our economies
In view of important connections with growth and stability, there is a growing interest from financial sector authorities, regulators, supervisors, governments, financial institutions, employers and innovators in understanding and advancing financial health and resilience at the household and macro levels.
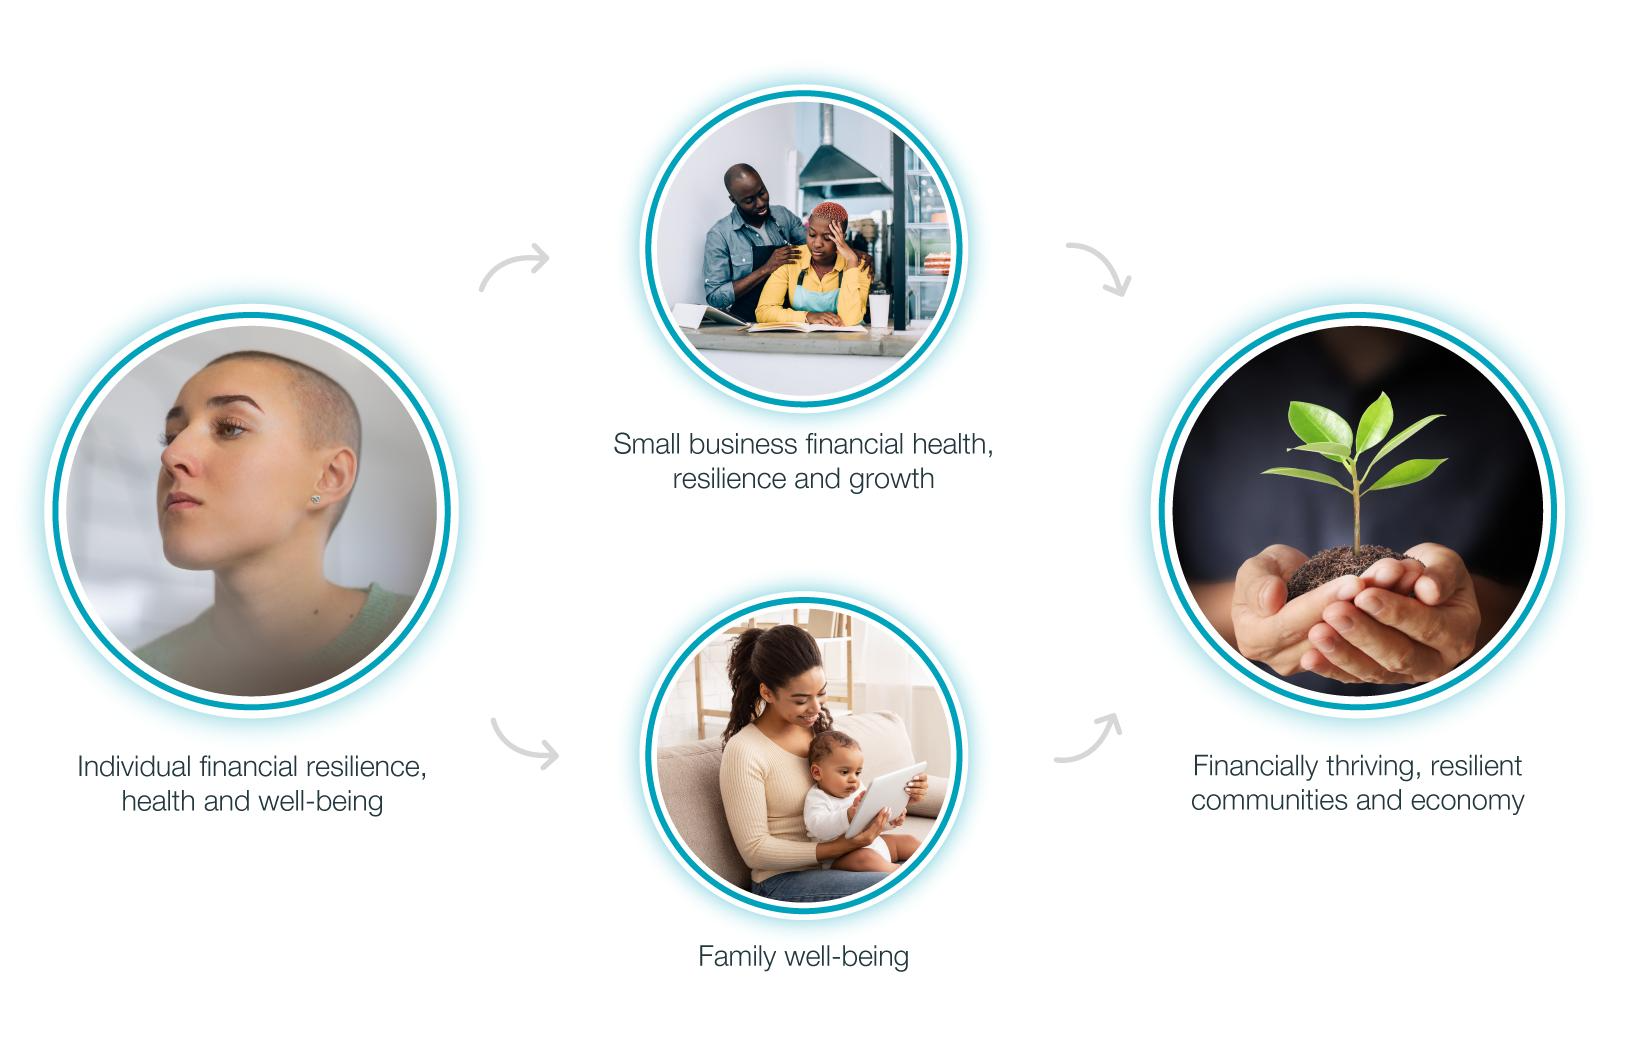
Turning access into meaningful and measurable impact
Financial health and resilience and financial well-being must be understood and measured holistically. The objective is not simply to expand access to financial services, but to determine whether individuals, families, businesses and communities are better able to manage their financial lives, withstand adversity, pursue opportunities and progress towards their goals.
Achieving this requires independent, evidence-based intelligence and human-centred solutions that put people and financially healthy lives at the centre. It also requires cross-sector collaboration, sustained outcomes measurement and continuous innovation.
Driving Systemic Change for a More Financially Healthy and Resilient World
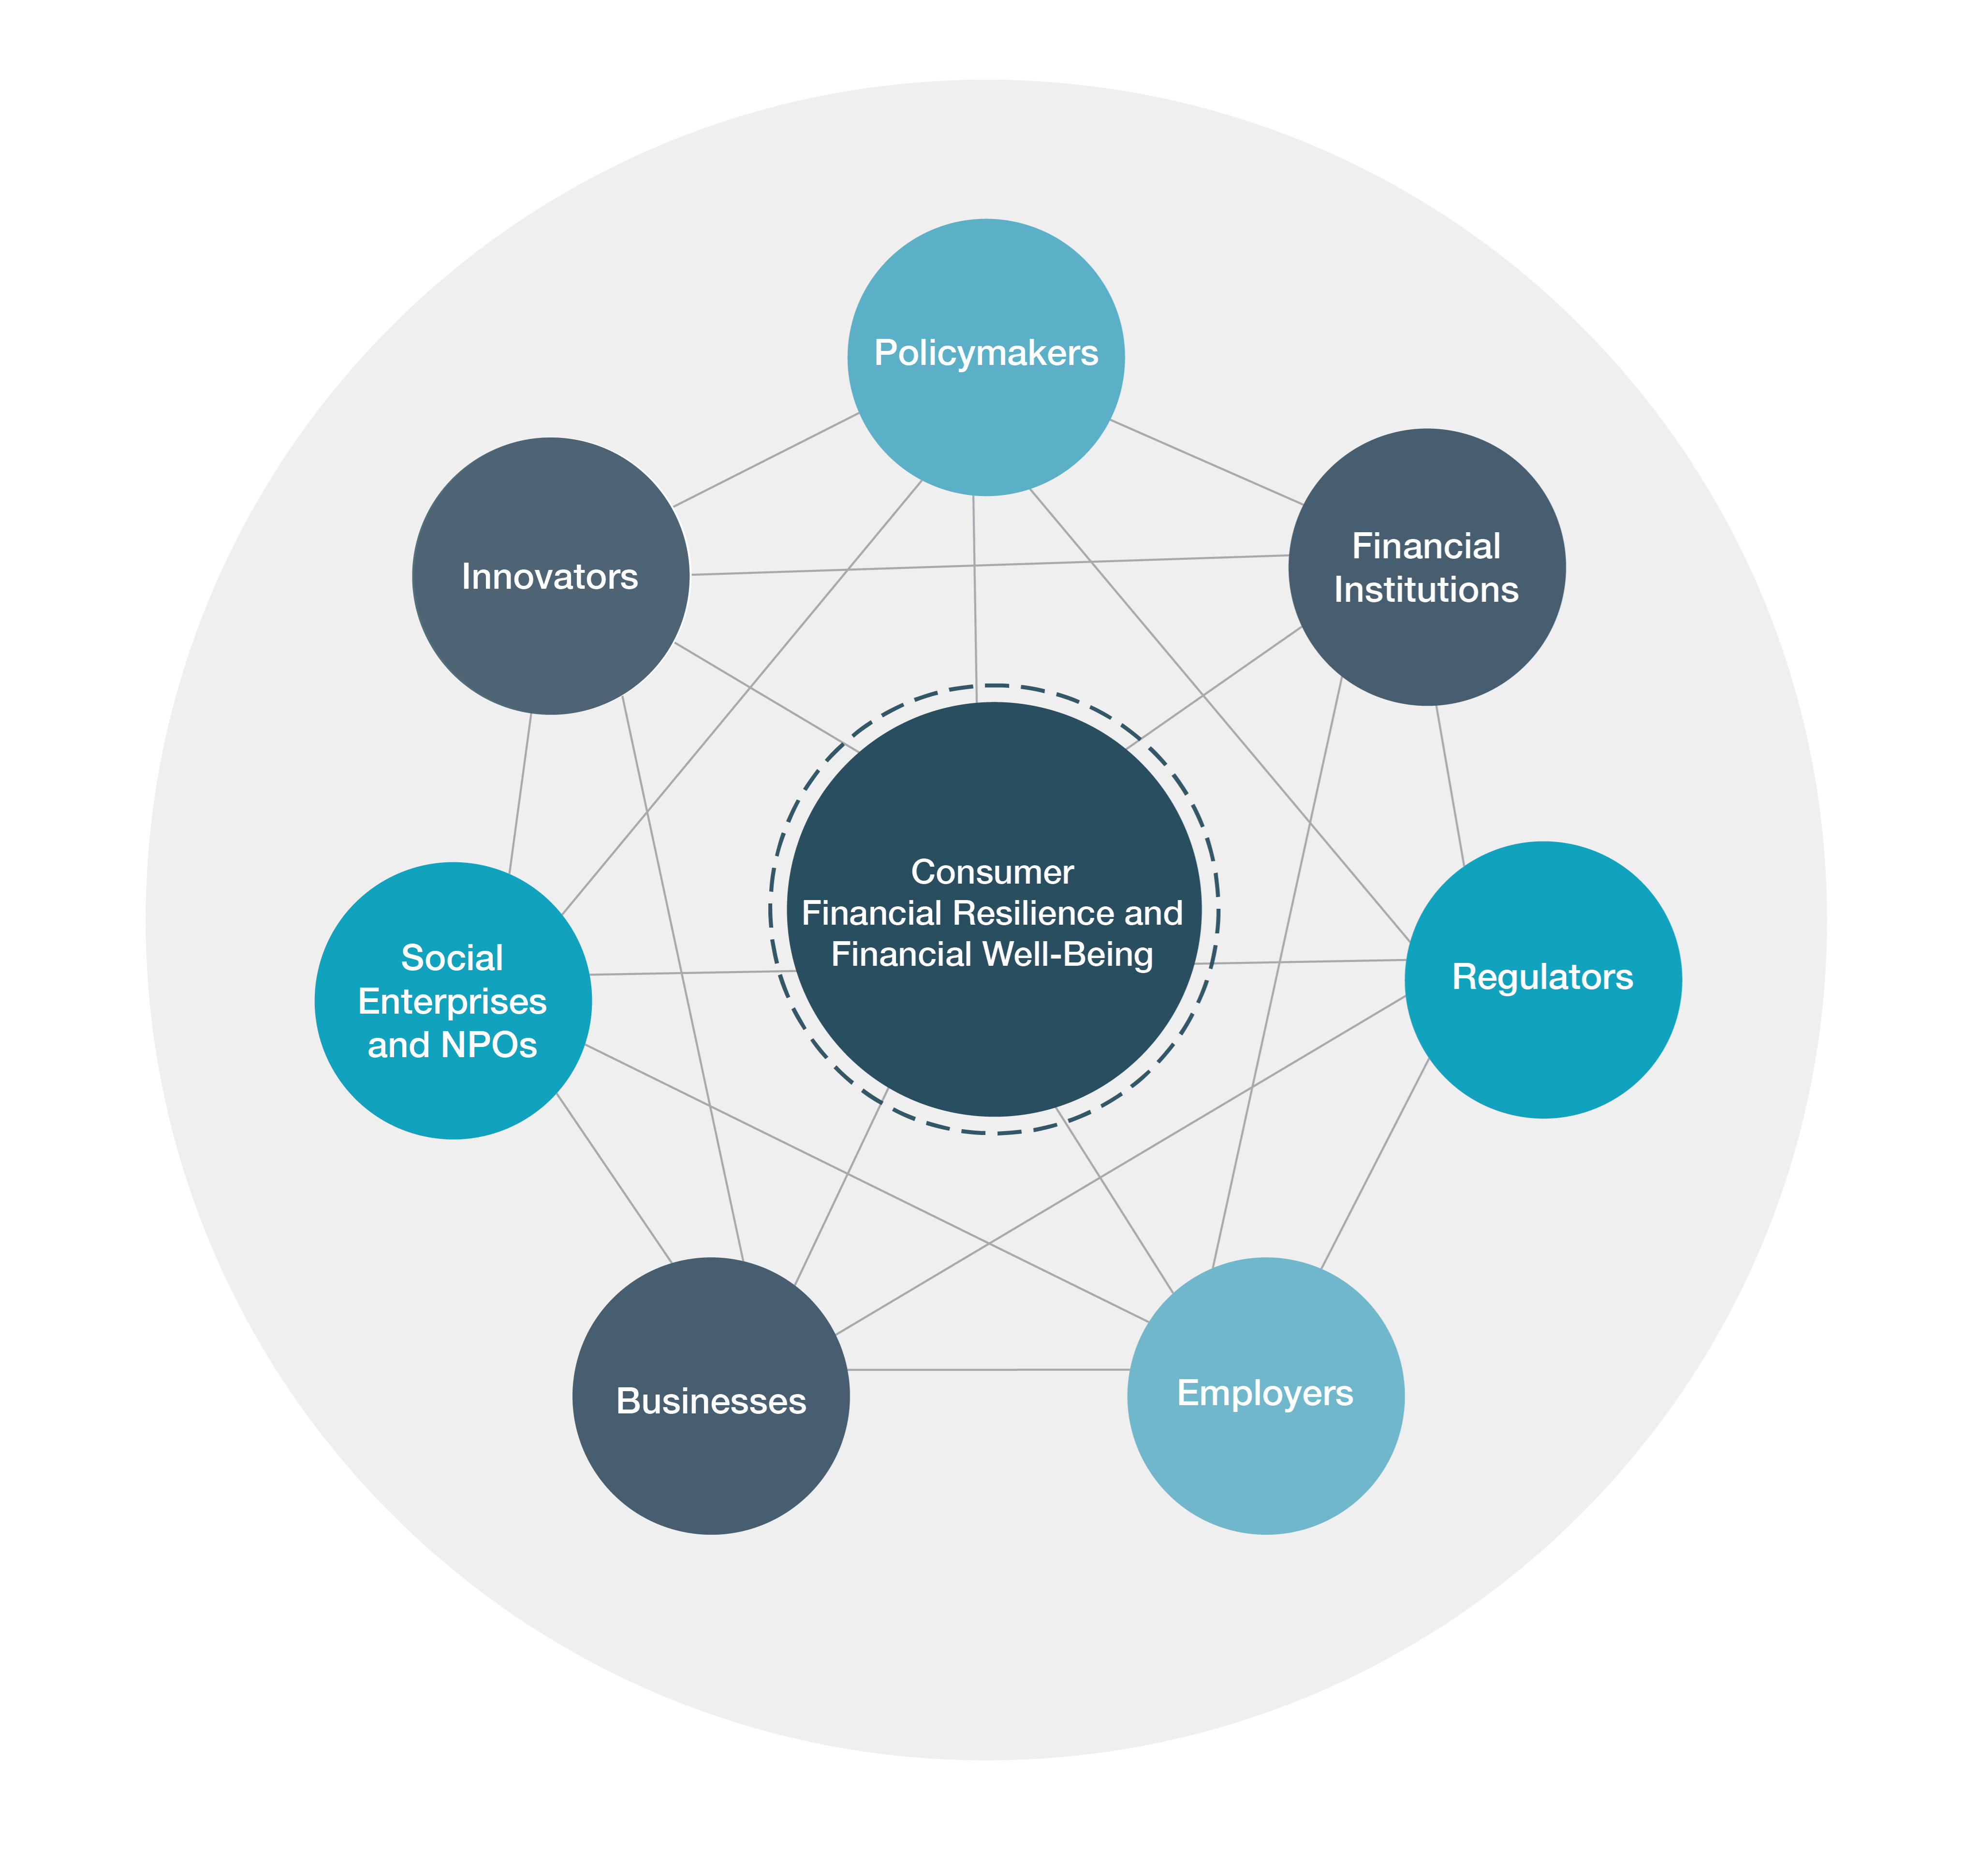
We're working to help build a more financially resilient future for people around the world, including those who are most financially vulnerable, underserved or need help most, by advancing systemic change through improved financial health, resilience and well-being. We're working alongside financial health innovators, clients and partners globally and support evidence-based decision-making, targeted impact and innovation at scale.
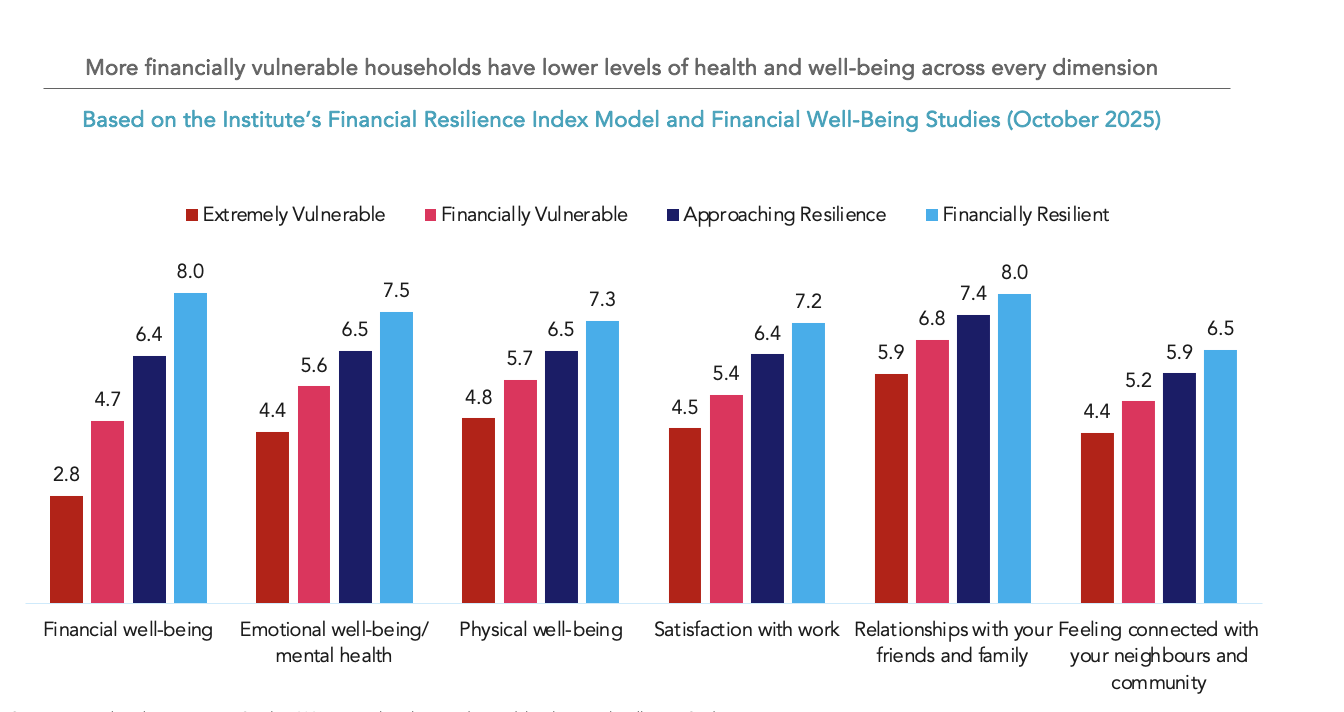
More financially vulnerable households have lower levels of financial well-being and all well-being dimensions; this is the social impact case for Policymakers and others working to help improve financial resilience and financial well-being. See our joint report with Statistics Canada published in 2021 with linkages to the government’s Quality of Life Framework.
By better understanding financial health and resilience, more nuanced fiscal, monetary, financial and social policy levers, policies and programs can be developed to help drive positive financial resilience outcomes with a sharpened aim at specific underserved and more vulnerable populations.
Planned and unplanned life events, stressors and shocks have effects at multiple levels, with financial resilience and financial well-being as enablers of overall resilience, health and thriving communities.
Global financial health innovation is advancing through the leadership and collaboration of the UNSGSA, UNEP Finance Initiative, CGAP, the Bank for International Settlements Financial Stability Institute, Financial Health Network, OECD and other leading organizations. The Institute is proud to contribute to this global movement, building on more than 15 years of dedicated financial health practice.
Together, we can contribute to more financially secure and empowered people, stronger businesses, improved well-being, more resilient economies and communities, and ultimately, a more inclusive and sustainable future for generations to come.
Find out more by accessing data and reports on, for example, economic inclusion and mobility, climate change impacts on household financial vulnerability or protection as a pathway to financial resilience.